Builders are expanding their focus beyond data centers, highlighting growth in transportation, energy, and infrastructure, as recent earnings reports reveal.
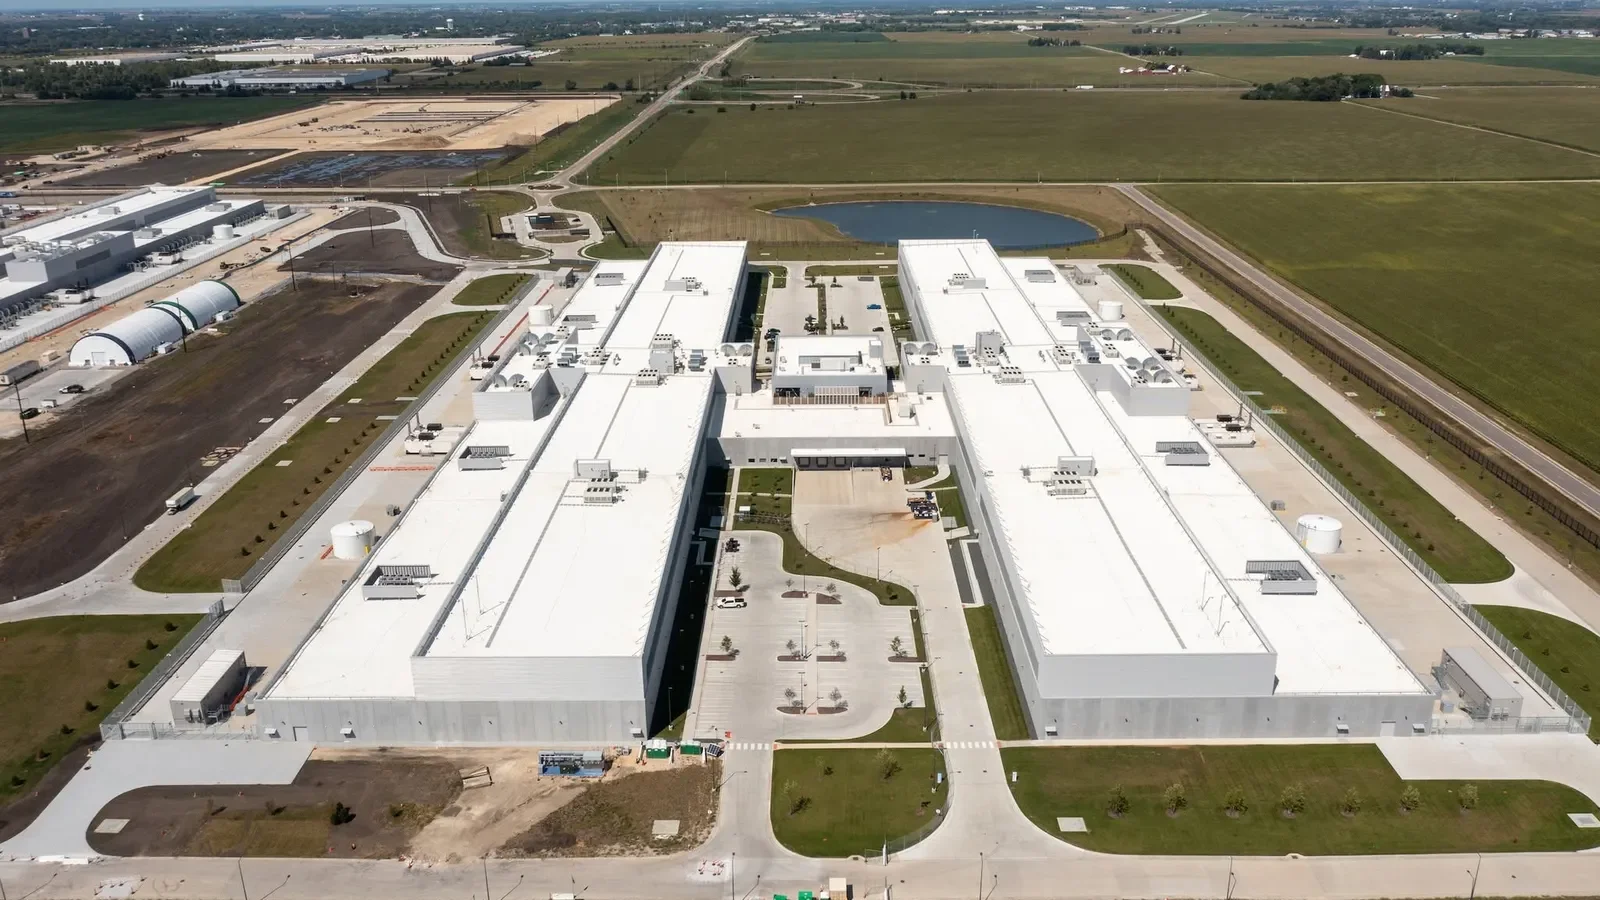
Balfour Beatty's CEO, Philip Hoare, encapsulated the current buzz in the construction industry: "You can’t pick up anything these days and not read about data centers." This sentiment reflects a broader conversation unfolding in the latest earnings reports from numerous public builders. While the surge in data center construction is undeniable, it also overshadows a weakening trend among smaller contractors.
The Emerging Dominance of Data Centers
Data center projects have significantly dominated the construction sector, creating a concentrated boom primarily benefiting larger companies. Evidence of this trend shows that firms with over $100 million in annual revenue reported a backlog of 12.1 months as of July. In stark contrast, smaller contractors, those with less than $30 million in revenue, faced a substantially lower backlog of just seven months. This disparity highlights the competitive advantage held by larger players in a market that is heavily reliant on data center builds, which in turn masks broader vulnerabilities that may be developing within the industry.
The rise of data centers can be attributed to several key factors, including an ever-increasing reliance on digital technology and cloud services. Businesses are not just building data centers; they’re racing against time to keep up with the demands of an increasingly digital-first economy. This isn't merely a trend; it's reshaping the entire construction paradigm. The construction focus has shifted, funneling resources toward this sector, which may leave other vital areas like residential or commercial developments underfunded. This is more significant than it looks — the ripple effects could be felt across the entire construction ecosystem.
Diversifying Portfolios: A Shift in Strategy
However, there's a noteworthy shift as many of these publicly traded firms are keen on diversifying their portfolios beyond just data centers. They are maintaining an active focus on varied infrastructure sectors such as transportation, aviation, energy, and significant megaprojects. This varied approach is critical as these companies navigate through continued uncertainty and evolving market demands. After all, relying on a single source of revenue can create perilous vulnerabilities, especially if market conditions change.
For instance, firms like Skanska and Granite are diversifying not just for the sake of being broad-based, but to capture growth in lagging sectors. In a volatile and competitive environment, companies are finding that they need to cast a wider net to sustain their financial health. This tactic lessens the dependence on data centers and allows firms to weather shifts in demand across different markets. It’s about survival, really. The unyielding focus on data centers might be the buzzword of the moment, but the underlying truth is that diversification can provide a buffer against unforeseen downturns.
Recent Earnings Reports Highlighting Diverse Successes
Recent earnings reports reveal specific successes amid this diversification effort:
-
Skanska reports record $7B order intake for Q2
Despite robust financial numbers, CFO Pontus Winqvist cautioned against drawing conclusions based on just one quarter.
-
Granite targets rail, roads and data centers amid growing backlog
The company's focus on data centers spurred a threefold increase in backlog, aiding overall revenue growth despite facing debt restructuring challenges.
-
Jacobs’ data center pipeline triples as backlog hits $28.9B
The company reported an accelerating demand for data center and semiconductor projects during its fiscal Q3 earnings call.
-
Tutor Perini rides megaprojects to record revenue, higher profits in Q2
With an eye on profitability, the contractor sees an opportunity in $200 billion worth of upcoming bids.
-
WSP capitalizes on surging US power work
CEO Alexandre L’Heureux noted that power generation now accounts for 40% of the company's revenue.
-
Fluor targets energy over data centers
Fluor's leadership indicated a stronger fit with energy projects, which better match their operational profiles.
-
AECOM touts data center pipeline amid fiscal Q3 loss
A significant revenue decline due to a $337 million charge couldn't overshadow their promising backlog in the recent quarter.
-
Balfour Beatty bullish on aviation, data centers in US
The U.S. segment, previously a challenge for the company, rebounded to profitability in the first half of 2026.
The Implications of Current Trends
As these firms navigate through challenges and opportunities, a diversified focus could ultimately position them for sustained growth beyond the current data center craze. But here's the thing: their focus on data centers might lead to other important construction sectors being neglected. The risks of such a one-track approach can manifest quickly, especially when economic circumstances shift.
If you're working in this space, the trend toward diversification in project portfolios could be a sign of broader industry awareness. Companies are waking up to the reality that excessive reliance on a single segment could be detrimental. The construction market thrives on variety and adaptability; a balanced portfolio can counteract downturns in specific sectors. This evolution is not just about profit margins—it's about sustaining the industry's health as a whole.
As companies shift their focus and take on new types of projects, the competitive dynamics may also change. Competition could become fiercer, but the chances for strategic partnerships or even mergers and acquisitions will increase. This means that firms will need to remain agile, constantly reevaluating their strategies based on market trends. This period will be critical for the construction industry as it adapts to both threats and opportunities on the horizon. Embracing change might just be the key to long-term viability in a sector that is anything but static.
Discussion
Sign in to join the discussion.