The Fed's interest rate hikes indirectly impact mortgage rates, influenced by inflation and economic performance, shaping the current borrowing landscape.
The Fed's Impact on Mortgage Rates: Myth and Reality
You may have seen recent headlines about the Federal Reserve (the Fed) increasing interest rates again. If you're in the market to buy or sell a home, you might be asking yourself how this affects you. There's a prevalent misunderstanding that the Fed directly controls mortgage rates, but that's not accurate. Their decisions certainly have ramifications, but they are just one of several influences on the mortgage landscape. If you’re in this industry, you must grasp how these dynamics shape today’s borrowing environment.Why Is the Fed Raising Rates?
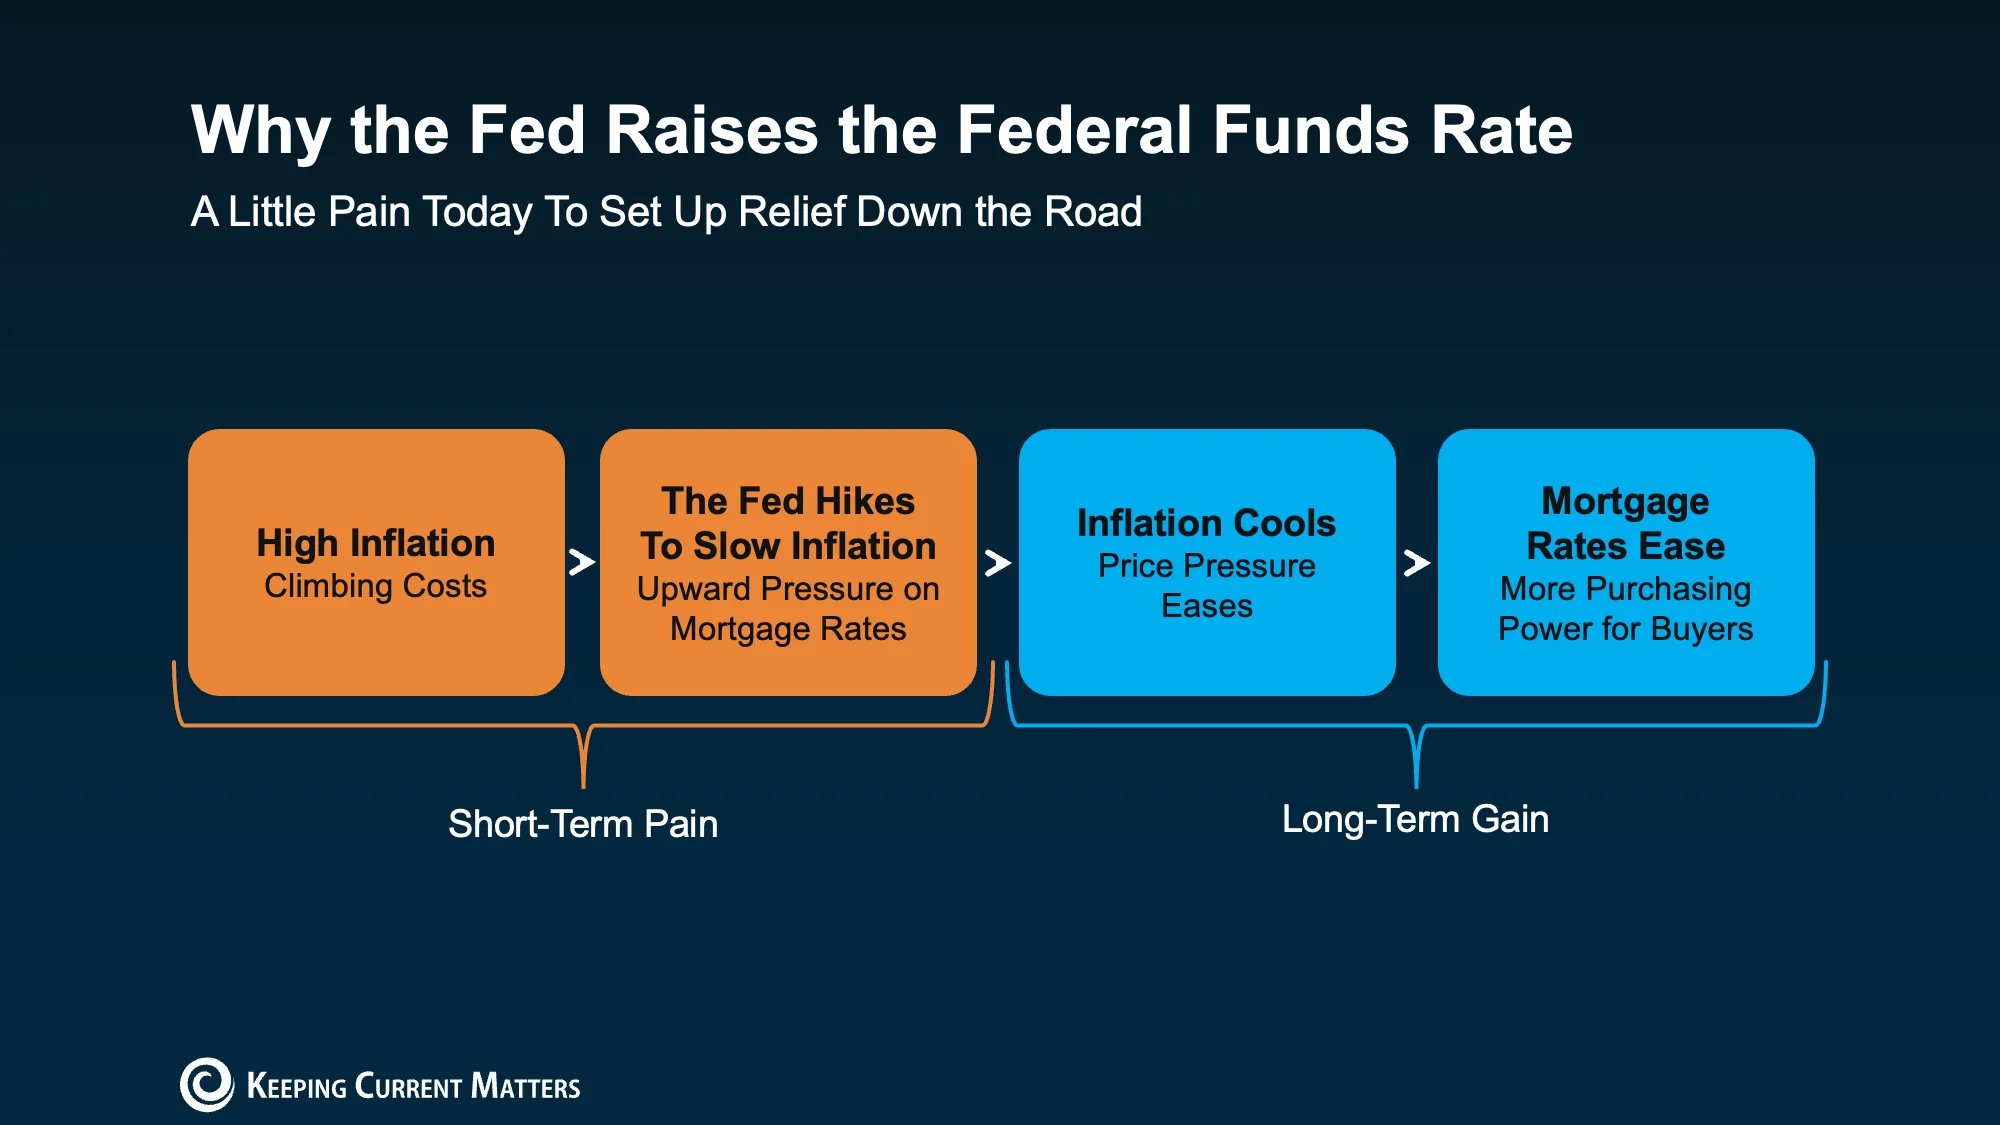
At the heart of the matter is inflation. As prices rise, buyers lose purchasing power, and home construction costs increase. To combat this, the Fed raises its benchmark interest rate, known as the Federal Funds Rate, which aims to temper inflationary pressures. However, this is where confusion often arises.- MYTH: The Fed sets mortgage rates directly.
- REALITY: The Fed influences mortgage rates among various factors that shape them.
Potential Rate Hikes Ahead
As per CME FedWatch, there’s a greater than 80% probability of another Federal Funds Rate increase by the end of 2026. Keep in mind, while the Fed doesn’t set mortgage rates directly, any additional hikes are likely to maintain upward pressure on them. This begs the question: should you hold off on buying or selling? Senior Economist at First American, Sam Williamson, advises that while stringent Fed actions could stabilize the bond market—leading to lower mortgage rates eventually—it hinges on investor confidence regarding inflation control. Despite inflation remaining above the Fed's desired target of 2%, there are signs it’s cooling more quickly than anticipated, evidenced by August’s data showing:- PCE inflation fell to 3.4%, down from 3.7% in July.
- Core PCE dropped to 3%, down from 3.3%.
Navigating the Current Market Conditions
Simply put, while this cycle of rate increases isn’t what many hoped for, waiting it out isn’t your only strategy. There are still viable paths forward.- If you’re buying: Get pre-approved to identify your budget. Work with your lender to secure the best possible rate, and be sure to lock it in once you're under contract to mitigate the risk of rate hikes before closing.
- If you’re selling: Clarify your priorities—whether that’s a swift sale or maximizing revenue. Pricing strategies should reflect today’s buyer capacities, which are constrained by current rates. Consider rate buy-downs or concessions; these can be more effective for affordability than just cutting prices.
Discussion
Sign in to join the discussion.