Unlocking Opportunities in Non-Agency Lending: A Focus on Home Equity Solutions
Published Oct 05, 2026833 readers
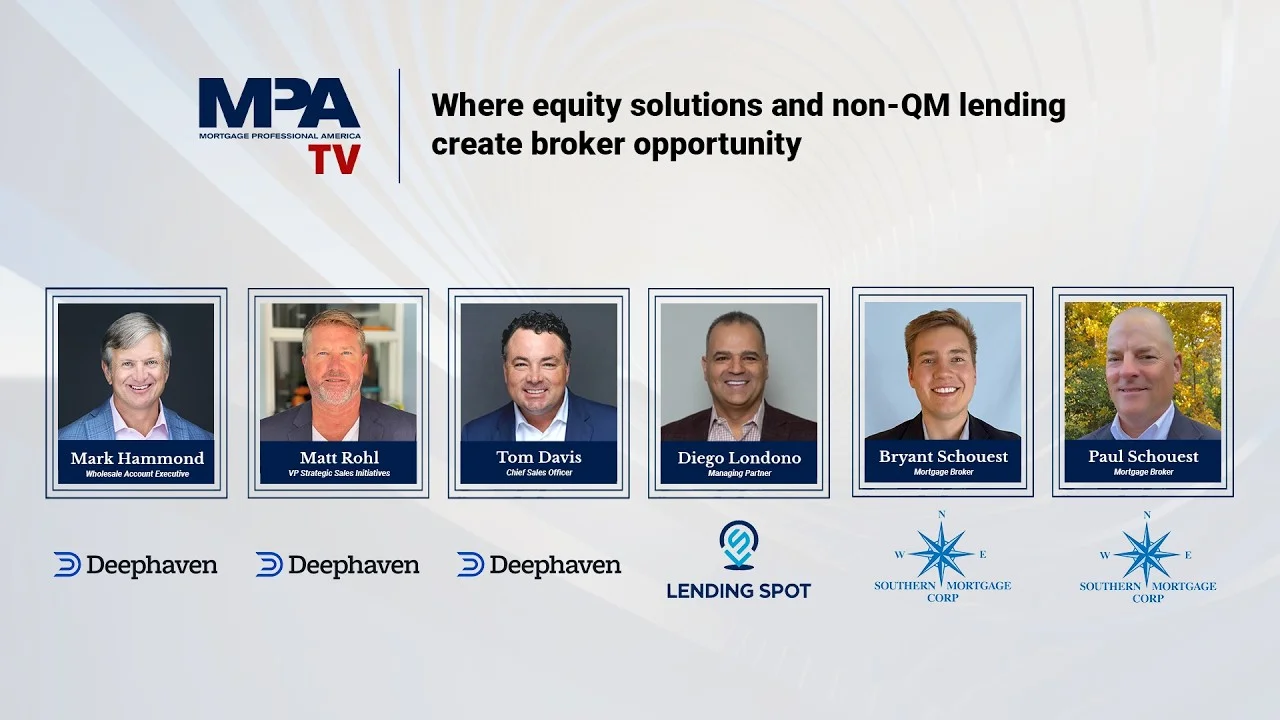
Non-agency lending is vital for brokers, with a projected $400 billion market, driven by home equity and renovation demands in tight housing conditions.
Seizing Opportunities in Non-Agency Lending
If you're not tapping into the non-agency lending market, you could be missing out on a significant slice of the business pie—potentially 20% or more of the available deals. This statistic isn’t just hype; it reflects a real shift in borrower behavior driven by current market conditions. Many professionals within the mortgage industry, particularly brokers, are finding that embracing non-QM (Qualified Mortgage) products is not only necessary but strategically advantageous. As one expert noted, this sector is projected to approach a staggering $400 billion in 2026. That’s not the future; that’s now.
Many brokers feel hesitant to offer these products, often due to lack of familiarity with their mechanics. However, the message from industry leaders is clear: stepping into this arena means staying competitive. “We shouldn't be shy offering these products," one industry expert stated, emphasizing that these offerings provide essential solutions for borrowers—especially those who are self-employed or looking to tap into substantial home equity. The focus here extends beyond mere financial transactions; it speaks to the need for lenders to adapt and provide bespoke solutions that align with changing consumer needs.
What's driving this demand? A combination of limited housing inventory and high consumer debt levels means homeowners are increasingly reluctant to move, opting instead to enhance the properties they already own. Reports indicate robust renovation activity, with projected expenditures in the renovation sector expected to reach $600 billion by 2026. The opportunity for loan officers to assist clients in accessing this capital isn't just a side note; it’s a pivotal strategy for thriving amid tight market constraints.
Harnessing Home Equity in a Tight Market
In this context, equity solutions have emerged as a generational opportunity. There are currently around 24 million millionaires in the U.S., with a significant majority accumulating their wealth through home equity. By upgrading what they already have instead of venturing into uncertain markets, homeowners are finding ways to leverage that equity for renovations and investments. It’s a different kind of consumer behavior, one that loan officers can capitalize on if they have the right tools in their repertoire.
The statistics are telling. For instance, a recent quarter saw $47 billion in equity extraction, with over half of that amount coming from equity products, primarily second liens. The clear implication is that if lenders aren’t formally integrating equity products into their offerings, they're at risk of losing clients to servicers who do provide these solutions. This reality is underscored by a whopping 90% recapture rate for loans serviced in this manner, highlighting just how crucial these products are for retention and client satisfaction.
What this means is straightforward: brokers need to be proactive. The current environment presents a chance to not only serve existing clients better but also to attract new ones—particularly self-employed individuals and savvy investors who can benefit from less conventional lending options. The reality is, if brokers are unwilling to expand into non-QM territory, they could very well find themselves outpaced by competitors ready to innovate.
So, if you're working in this space and facing growing competition, consider this your wake-up call. The market is ripe with opportunities, but only for those who are willing to adapt and embrace the tools healthily aligned with the evolving needs of today’s borrowers.
Looking Ahead: Equity Solutions and Market Dynamics
What stands out in this discussion is the palpable excitement around equity solutions and their transformative potential for brokers and their clients. The integration of innovative products, such as digital Home Equity Lines of Credit (HELOCs), is proving effective in reconnecting with past borrowers. This segment emphasizes not just the popularity of these solutions, but their genuine capacity to meet the financial needs of homeowners grappling with existing debt or planning renovations.
For many professionals in this space, maintaining a robust database of past clients is more than a good practice; it’s a goldmine. As the conversation hinted, the ability to reach out to clients and offer tangible solutions—like cash for renovations or debt consolidation—can significantly bolster client relationships. The reluctance some clients feel in discussing their financial situations, particularly when it comes to debt, means a sensitive approach is necessary. Tools like digital calculators can empower consumers, breaking down barriers and encouraging proactive engagement in financial discussions.
Here's the thing: the landscape of mortgage and equity lending isn't just shifting; it's rapidly evolving. With projections of continued growth in the non-agency market—30-35% year-over-year—the opportunity for loan officers to harness these equity products couldn't be clearer. Whether you're grappling with the intricacies of loan officer adoption or addressing the unique needs of your clientele, embracing these equity solutions seems imperative.
That said, it won't be without its challenges. The role of loan officers will undoubtedly shift as they navigate this growing segment while maintaining their traditional roles. The flexibility to focus on not just current homeowners but also those who are financially unencumbered offers fresh avenues for growth that many brokers might overlook. A proactive outreach strategy, coupled with a deep understanding of the available products, could be key to thriving amidst stiff competition.
As the market functions under the weight of economic uncertainty and shifting lending criteria, it's clear that those who adapt will likely come out ahead. Brokers need to lean into this wave of change, not only to serve their existing clients better but also to forge new connections that can yield long-term partnerships. For those in the industry, mastering the nuances of non-agency and equity products seems not just beneficial, but essential.
The message is clear: those who approach this market reset with a blend of innovative solutions and a customer-first mindset are positioning themselves to lead the conversation and potentially carve out a significant stake in a rapidly growing sector. As we look ahead, the choices made today will undoubtedly shape the terrain of tomorrow's real estate finance landscape.
Discussion
Sign in to join the discussion.