Discover essential actions you can take to influence your mortgage rate amid rising costs, including credit management and loan options.
The current dynamics of the housing market are challenging for potential buyers, particularly when it comes to affordability. With mortgage rates trending upwards, many are left reconsidering their timing in the home-buying process. The broader economic factors at play, including inflation and market psychology, amplify the concern, making the landscape feel even more daunting for first-time buyers or those looking to upgrade their homes.
Understanding Rising Mortgage Rates
Recent data from Mortgage News Daily indicates that rates have surged significantly this year. This upward trend can be attributed to various factors, including economic indicators, inflation, and even global events affecting financial markets, in addition to actions from the Federal Reserve, who recently lifted their Fed Funds Rate. Understanding the driving forces behind these fluctuations requires a closer look at both domestic and global economies.
The Federal Reserve's decisions are, of course, not made in a vacuum. Actions such as raising interest rates aim to curb inflation but can inadvertently lead to increased borrowing costs for individuals. In recent months, this has left prospective homebuyers grappling with the implications; not only are homes more expensive, but the monthly costs associated with financing are also becoming a more significant burden. As Danielle Hale, Chief Economist at Realtor.com, notes:
“The pressure on mortgage rates was here even before the Fed rate hike, and it doesn’t show signs of relenting...”
Strategies to Counteract Rising Rates
While the rising rates may be concerning, there's still a degree of control you can exert over your mortgage situation. Here are three critical areas to consider that could help shape the interest rate you ultimately secure. Understanding these strategies might not only improve your financial situation but could also empower you to make a more informed purchasing decision.
Improve Your Credit Score
Your credit score significantly influences the rate you'll be offered. Even small improvements can lead to lower monthly payments, which is especially important when overall affordability is at risk. A good credit score isn't just a number—it's a reflection of your creditworthiness that lenders weigh heavily in assessing risk.
“Generally, the higher your credit score, the more options will be available to you, including better loan terms and a lower interest rate.”
Improving your credit score should, therefore, be a priority. This might mean paying down existing debts, ensuring bills are paid on time, or even correcting any inaccuracies on your credit report. If you’re uncertain about your current score or how to enhance it, consulting with a knowledgeable loan officer could provide valuable guidance. They might be able to offer suggestions tailored to your specific situation, which can be invaluable in this tough market.
Assess Your Loan Options
The type of loan you choose has a direct effect on your mortgage rate. Conventional, FHA, VA, and USDA loans each come with distinct requirements and corresponding rates. Beyond that, the length of the loan term—whether it's 15, 20, or 30 years—will also affect both your payment and total interest over the life of the loan. According to Bankrate:
“… rates on fixed-rate loans are typically higher than introductory rates on adjustable-rate loans because the fixed-rate lender takes on the risk that rates could increase during the loan’s term.”
It's essential to work with a lender to explore the various loan options available. There’s no one-size-fits-all solution here. Having conversations with multiple lenders can help you identify optimal terms that align with your financial situation and long-term goals. What this means for you is being proactive; jumping in without assessing your options might leave you with a less favorable rate than your peers.
Consider New Construction
When it comes to purchasing a home, the type of property can certainly affect your mortgage rate. Many builders currently offer incentives, such as buying down rates, which can lower your monthly payments. This trend is particularly pronounced in the new construction sector, where competition among builders is fierce and incentives abound.
In fact, Realtor.com has recently reported that buyers of new homes enjoyed lower average rates than those purchasing existing homes last quarter. This discrepancy is telling; new builds often come with the latest construction standards, which can translate into lower utility costs over time.
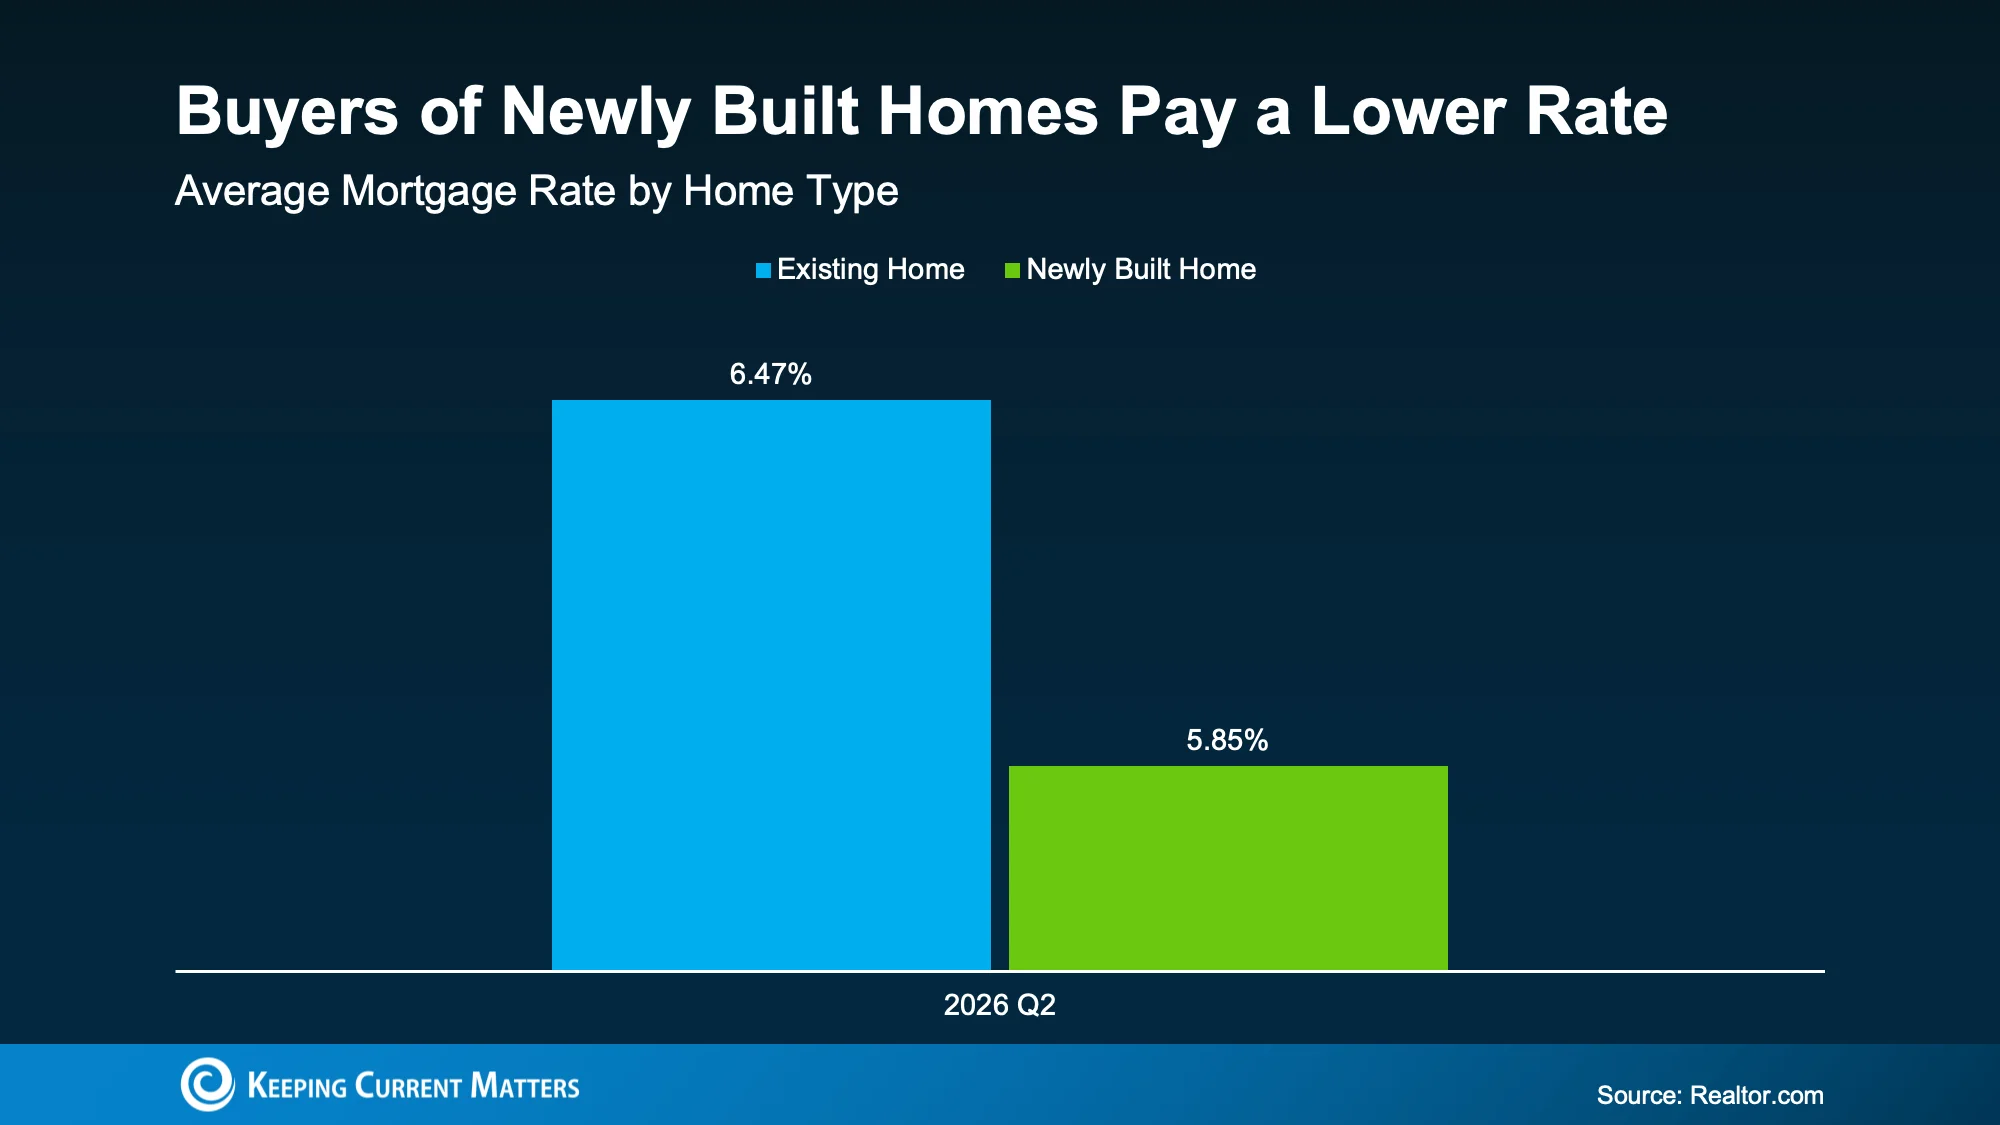
If securing a lower rate is a priority for you, don’t hesitate to ask your real estate agent to explore newly built communities that may offer such incentives. It’s a strategic move that could yield significant long-term savings.
Future Outlook and Market Significance
The current situation in the housing market reveals more than just rising rates; it uncovers broader issues of affordability and the economic pressures facing potential buyers. If you're working in this space, understanding these dynamics is essential for navigating your own home-buying journey. The implications of rising rates might not only affect your immediate financial landscape but could also shape market trends moving forward.
As buyers adapt to these trends, we might see a shift in demand towards particular types of properties or financing mechanisms that provide relief amid high rates. The bottom line is clear: although you can’t dictate the direction of mortgage rates, you do have control over your credit score, your choice of loan, and the type of home to purchase. Partnering with a skilled lender will help you secure the best possible rate, and when you’re ready to make a move, a savvy local real estate agent can assist you in navigating this complex market.
Discussion
Sign in to join the discussion.